
On May 14, the US Senate Banking Committee advanced the Digital Asset Market Clarity Act through markup, the most significant step yet toward a comprehensive federal framework for crypto markets. The bill has been years in the making, and continues to navigate a labyrinth of competing interests across the banking sector, the crypto industry, and regulatory agencies. But at the heart of the bill’s journey lies a disputed question that has fuelled negotiations thus far: should stablecoins be allowed to pay yield?
The version of the Bill passed by the recent Senate Banking Committee banned yield from being offered on stablecoin holdings; instead, it permits rewards on bonafide stablecoin transactions. This is because yield-bearing stablecoins bear a strong resemblance to interest generating bank deposits, positioning stablecoin issuers and their products as direct competitors to banks. It took months of back and forth between the crypto industry and the banking lobby to arrive at the current prohibition, and banking lobbies are still pushing for tighter restrictions through rule-making. Unpacking why raises some fundamental questions: who controls our money and what happens when that control shifts.
The GENIUS Act Set the Stage
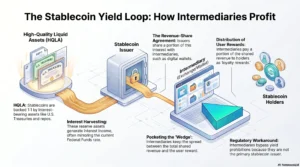
Understanding the yield issue’s centrality to the CLARITY Act would first require understanding that Act’s predecessor: The GENIUS Act of 2025. GENIUS established the foundational framework for stablecoin regulation in the United States. It obligated stablecoin issuers to a straightforward requirement: they had to back their tokens one-to-one with high-quality liquid assets such US Treasury bills, cash, or equivalent instruments. Every dollar of stablecoin in circulation had to be matched by a dollar of safe, liquid reserves. The model that then emerges is this: stablecoin issuers back their tokens with reserves of US Treasury bills and make money by capturing the yield the US government pays on that sovereign debt. The success of this arrangement relies heavily on sovereign solvency, i,e, the US government making good on its promise to repay its lenders.
This is fundamentally different from how traditional banks operate. Banks rely heavily on deposits to facilitate their lending activities. When an individual deposits their household savings with banks, banks do not simply hold this money. They lend it out to businesses, entrepreneurs, and other borrowers. From the interest they get from borrowers, they return a portion to depositors as yield and keep the difference, the spread, as their own earnings. The bank, in other words, is an intermediary between household savings and productive economic activity. Its returns depend on the real economy performing.
This is a wholly different relationship with money than what stablecoin issuers share. The stablecoin issuer does not need the free market to perform, nor does it need businesses to grow or borrowers to repay. It needs only one thing: the US government to fulfil its Treasury obligations. Once it does, the issuer shares a portion of that yield with intermediaries like crypto exchanges and digital wallet providers who pass some of it on to token holders in the form of rewards. This ensures token distribution and market adoption, but the whole system is underwritten by the US government paying its debt.
Are Stablecoins Completely Reallocating Trust?
At present, more than 97% of total stablecoin value is pegged to US dollars, meaning that a large volume of the stablecoins in circulation rely on the US honor code. If the GENIUS Act compels issuers to form a heavy reliance on the US government, stablecoins operate in practice as de facto government-backed instruments rather than purely private money. This creates two concerns. One, this represents a profound philosophical pivot for the crypto industry. The animating vision of crypto was a financial system governed by code rather than by sovereign promises, the antithesis of a world where your financial security depends on whether a government decides to honour its obligations. But today’s stablecoin ecosystem relies entirely on the U.S. sovereign state and its financial health.
What exists today is a structural irony: the largest stablecoin issuers in the world, Tether and Circle, between them control roughly $267 billion in stablecoin supply and are among the largest holders of US Treasury bills outside sovereign wealth funds and central banks . Their entire business model rests on the US government not defaulting. If Washington were to miss a debt payment, or if confidence in US sovereign creditworthiness were to waver, the reserve assets backing these tokens would immediately come under pressure, and the stablecoins themselves could break their pegs.
Consequently, the second concern that emerges is this: could stablecoin issuers themselves become conduits for financial contagion? In the event the state defaults, or if Treasury bills lose or are perceived to lose market value, stablecoin issuers might find themselves under-collateralised. Losses in reserve value could trigger stablecoin runs, possibly sparking an instantaneous, massive rush by holders to redeem their tokens, unfolding much faster than regulators or central banks could intervene . As a result, stablecoin issuers may be forced to liquidate their remaining reserve assets at deeply depressed “fire sale” prices, triggering cascading liquidations across crypto and traditional financial ecosystems. Rather than being immune to such issues as safe-asset market shocks or custodial institution failure, crypto institutions could find themselves front and center of a financial meltdown.
The Competition Argument and Its Limits
Another concern with this model is that growing stablecoin reserves can quietly redirect global household savings toward US sovereign debt rather than productive private lending. As more people invest in stablecoins, and issuers absorb increasing quantities of Treasury bills, the credit that would have flowed to local businesses through the banking system instead flows to Washington. Stablecoin advocates have a response to all of this, and it is not without merit. Their argument is that yield-bearing stablecoins will not deplete bank deposits but discipline banks. If consumers can earn a competitive return by holding a stablecoin, banks will be forced to raise deposit rates, improve their products, and compete more aggressively for customer funds. The result, they argue, is a healthier, more innovative financial system that better serves ordinary savers.
A recent paper by the Bank for International Settlements, however, highlights that the real-world dynamics may be more complicated. In a recent research paper, the BIS examines the emergence of what it calls Multifunction Crypto Intermediaries (MCIs), platforms that combine exchange services, custody, lending, yield products, and margin financing into a single entity. These intermediaries perform many of the same functions as traditional prime brokers and banks: they take in deposits in the form of stablecoin holdings, they lend them out, they manage collateral, and they generate yields through leverage and credit transformation. The critical difference is that they do much of this outside the prudential regulatory perimeter that applies to banks, without the capital requirements, liquidity ratios, and deposit insurance that protect the system when things go wrong.
This creates a troubling asymmetry. Banks are subject to expensive compliance obligations and capital requirements, while crypto intermediaries offer functionally similar products under significantly lighter rules. The competition stablecoin advocates promise is therefore not competition between equals; it is competition between a heavily regulated incumbent and a lightly regulated challenger, which tends to end not in innovation but in regulatory arbitrage.
There is also the question of where stablecoin reserves actually flow. When consumers move deposits from a community bank into a stablecoin, the issuer pools those reserves and parks them primarily at large, systemically important financial institutions like the mega-banks that act as custodians and counterparties for Treasury operations. The deposit does not disappear from the banking system, but it does migrate away from the local bank that was using it to fund small business loans in a regional economy, to a global custodian that recycles it through the Treasury market. The credit that local businesses and households depend on is quietly withdrawn. The community banking sector, already under structural pressure from fintech competition and rising rates, bears the cost.
The Global Stakes
These dynamics do not stay contained within US borders, and for emerging economies, the risks are amplified considerably. The BIS has outlined three scenarios for stablecoin adoption in emerging markets, and the most concerning, which it considers one of the more plausible near-term trajectories for vulnerable economies, is what it calls “digital dollarisation”. This is the scenario where dollar-pegged stablecoins, easily accessible via smartphone, become the de facto savings and payment infrastructure for citizens in countries with weak currencies or high inflation. Residents shift their savings into dollar stablecoins not because they want to use a crypto product, but because they want dollar stability and a yield they cannot get from their domestic bank.
Indian households are already demonstrating a structural shift, moving savings away from traditional bank fixed deposits and toward market-linked instruments. But it is important to consider: what happens if frictionless access to yield-bearing, dollar-backed stablecoins becomes widely and easily available; accessible from a smartphone, without a bank account, offering returns competitive with domestic deposit rates? The risk is not hypothetical. Savings that would otherwise sit in Indian bank deposits may move instead into dollar-denominated digital instruments whose reserves are held in US Treasury bills. This could enable digital dollarization, feeding directly in the US agenda, and endanger domestic credit creation and the lending cycle underpinning the economy.
What the CLARITY Act Is Actually Doing
The CLARITY Act’s stablecoin yield provision is, in this light, less a concession to bank lobbyists and more a recognition of a structural reality: that stablecoins have grown too large, too interconnected, and too globally consequential to remain outside the regulatory perimeter that governs comparable financial instruments. Section 404 does not seek to kill stablecoin innovation. It seeks to draw a line between two fundamentally different activities: using a stablecoin as a payment tool, which is a genuine and valuable innovation, and using it as a yield-generating savings product that competes directly with bank deposits, redirects credit away from the real economy, and concentrates systemic risk in an infrastructure with no safety net.
That distinction matters not just for American banks and American households, but for every economy that has quietly absorbed dollar stablecoins into its financial plumbing. A regulatory framework that gets this right, that preserves the payment innovation while containing the deposit substitution risk, is not an obstacle to the growth of digital finance. It is the foundation on which that growth can be sustained. A framework that gets it wrong risks creating a privately governed, sovereign-dependent monetary system that is simultaneously too embedded in the global economy to fail and too lightly regulated to be safely rescued when it does.
References
- American Bankers Association, Bank Policy Institute, Consumer Bankers Association, Financial Services Forum, Independent Community Bankers of America, & National Bankers Association. (2026, May 8). Letter to The Honorable Tim Scott and The Honorable Elizabeth Warren regarding Section 404 of the CLARITY Act.
- Council of Economic Advisers. (2026, April). Effects of stablecoin yield prohibition on bank lending. Executive Office of the President of the United States.
- Nigrinis, A. R. (2025, October 10). The lending impact of stablecoin-induced deposit outflows. Legal Economics LLC.
- Lenz, J., & Tymcio, R. (2025, September 19). Genius at work in the US financial system. Preprints.org. https://doi.org/10.20944/preprints202509.1566.v1
- Pinakiewicz, T. (2026, May 7). Stablecoins, the GENIUS Act, and the evolving structure of dollar finance. Galaxy Research.
- Hentov, E., Thiagarajan, R., Gorshkov, V., & Im, H. (2025, August). The stablecoin moment. State Street.
- Garcia Ocampo, D., Goodrich, P., & Lovicu, G.-P. (2026, April). Cryptoasset service providers as financial intermediaries: Risks and policy approaches (FSI Occasional Paper No. 27). Financial Stability Institute, Bank for International Settlements.
- Ray, A. (2026, January 30). No FDs please: Indian households’ financial savings strategy changes. The Economic Times; The Times of India. (2026). Fundamental shift from savers to investors: What are Indian households doing with their money? The Times of India.