
The Fed decides at 11:30 PM IST. Kevin Warsh’s first meeting as Chair is priced for a 25 bp hike, the first US rate move up since 2023. Dot plot is the trade.
TLDR
- Fed decides at 11:30 PM IST tonight. Rate futures put the odds at 93% for a 25 bp hike, the first US rate move up since 2023, taking the target range to 3.75-4.00%.
- Warsh’s press conference at 12:00 AM IST and the fresh dot plot decide whether the S&P 500 holds 7,585 or gaps lower.
- Bond market has already moved. 10-year Treasury yield touched 5.00% Tuesday, the highest in nearly two decades.
- Senate blocked the CLARITY Act cloture vote 50-41 Monday, ending US crypto market structure hopes for 2026. HOOD dropped 7.22% to $106.08, COIN fell about 9%, CRCL about 5.5%.
- SK Hynix publicly denied talks with Intel on US memory chip production. INTC closed essentially unchanged at $97.14.
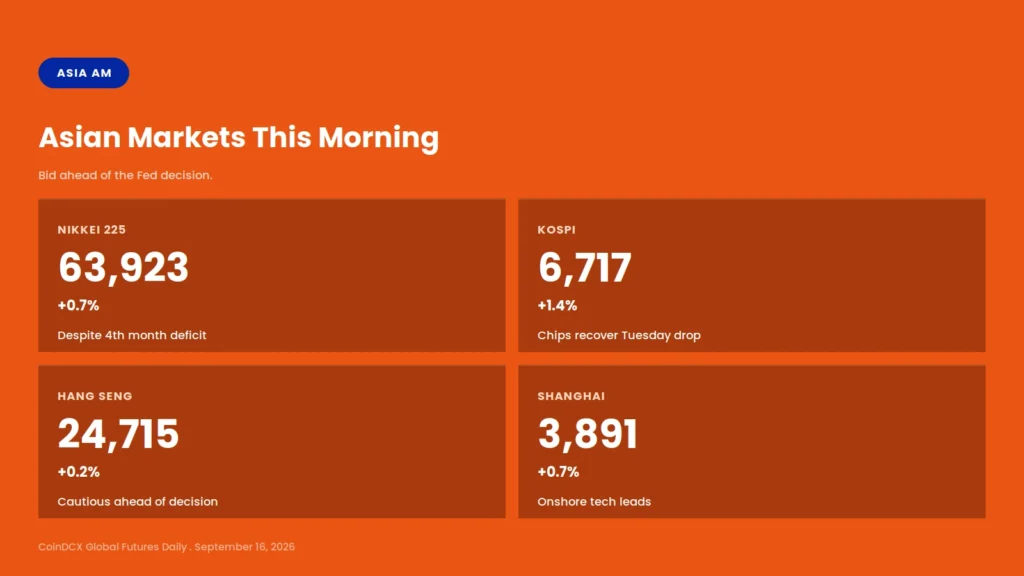
- Asia is bid ahead of the decision. Nikkei +0.7% at 63,923, Kospi +1.4% at 6,717.97, Hang Seng +0.2% at 24,715, Shanghai +0.7% at 3,891.60.
Market Regime
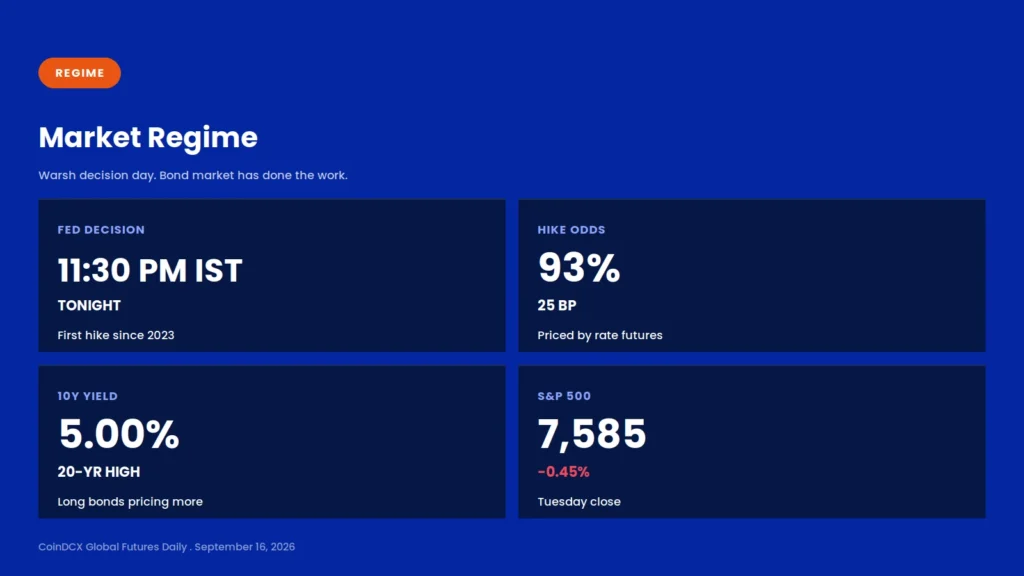
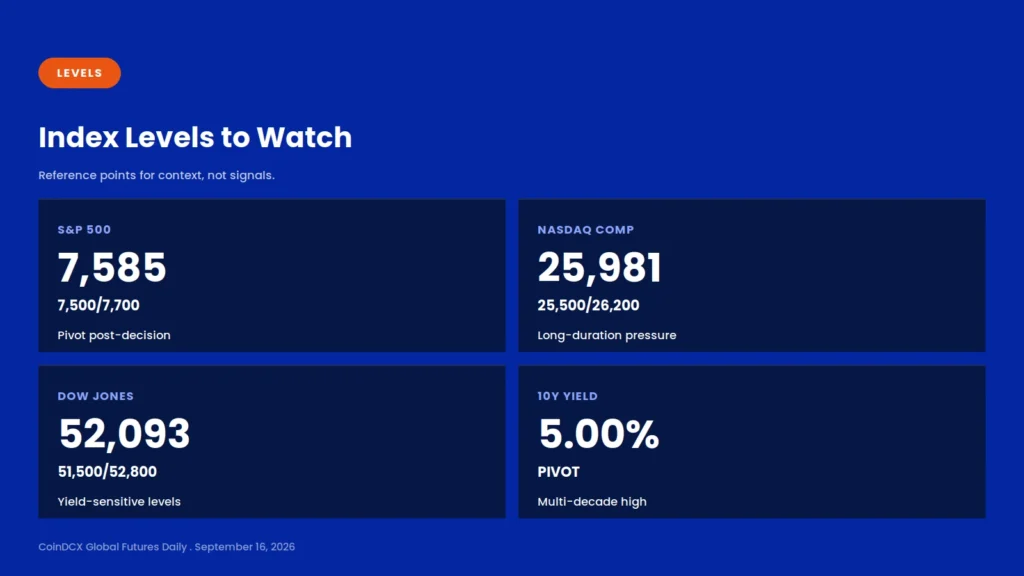
The tape enters the Warsh decision with everything but the press conference already priced. Rate futures show 93% odds on a 25 bp hike, which would take the Fed funds target range from 3.50-3.75% to 3.75-4.00% and mark the first US rate hike since 2023. The 10-year Treasury yield closed Tuesday at 5.00%, the highest in nearly two decades, and long bonds are pricing this hike plus more. The S&P 500 is holding 7,585 with the Nasdaq at 25,981, both marginally lower Tuesday as traders refused riskier bets.
What can break the tape is the dot plot and the presser tone, not the hike itself. If the September dot plot pencils in two more hikes for 2026, the curve steepens further and long-duration tech gives up more ground. If Warsh signals this is the last move for the year, equities have room to rally into Thursday. JPMorgan flagged the alternative tail risk: if Warsh does not hike, the S&P 500 downside is 1.25% to 1.75%, because a dovish surprise would call the Fed’s inflation resolve into question with oil at $109 and yields at multi-decade highs.
Bullish Factors
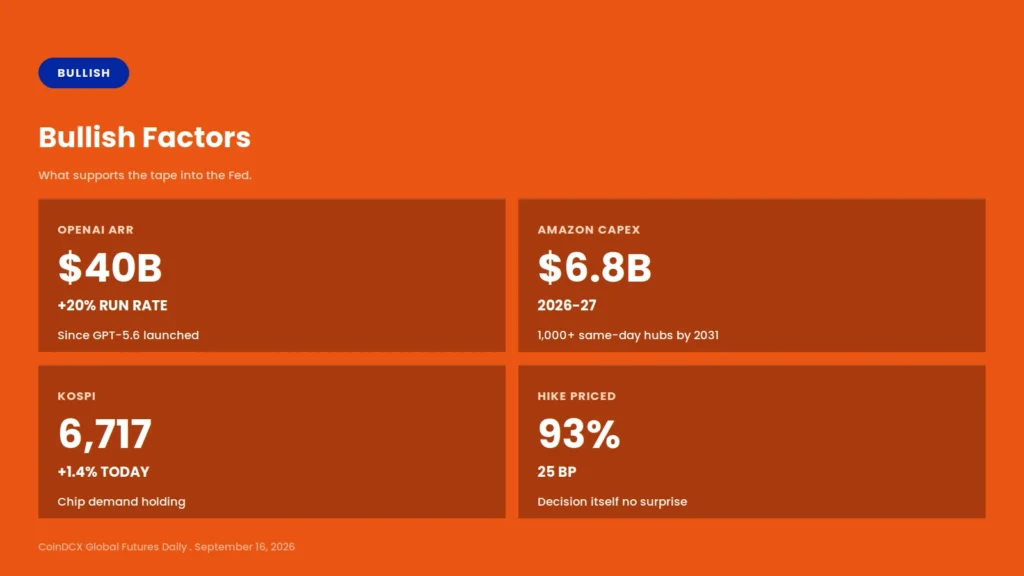
- Fed hike is fully priced. The 25 bp move is 93% priced in, so the decision itself is not the surprise. A cleanly delivered hike with a measured presser can be a relief for equities.
- Amazon backed up its capex signal. Announced 1,000+ new same-day delivery hubs by 2031 with $6.8B budgeted for 2026-27 alone. Big real economy investment continues into a higher rate regime.
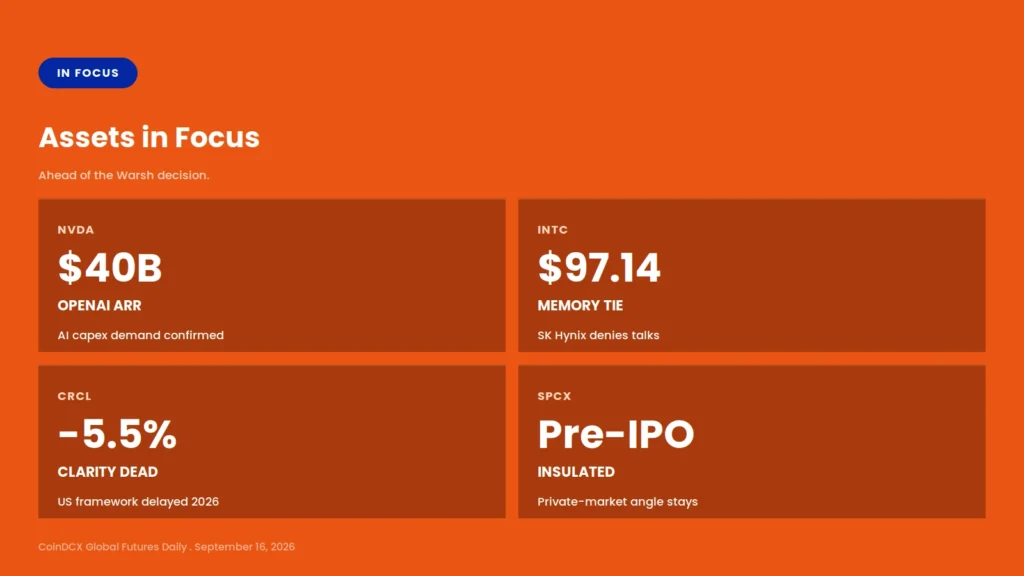
- OpenAI revenue is real. Annualized run rate cleared $40B last month, up about 20% since GPT-5.6 launched. The customer revenue side of the AI capex trade is showing up.
- Memory supply story is intact. SK Hynix denial on Intel is Intel-specific and does not touch HBM demand for AI accelerators. Kospi +1.4% overnight backs this read.
- Asian markets are bid ahead of the decision. Nikkei, Kospi, Hang Seng, and Shanghai are all green this morning despite Wall Street losses Tuesday.
Bearish Factors
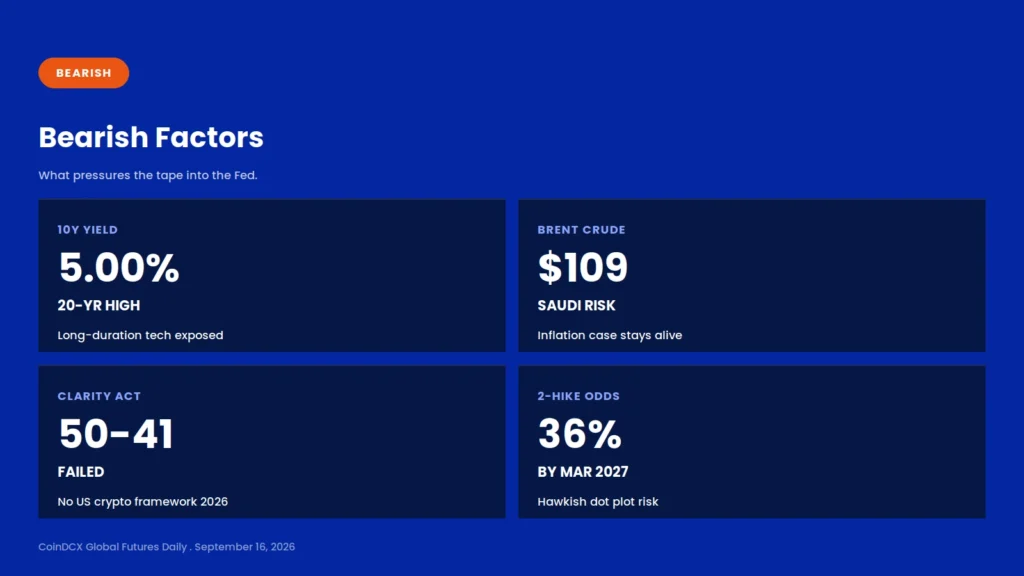
- 10-year Treasury yield at 5.00%. Highest in nearly two decades after a weak $13B sale of 20-year bonds Tuesday. Higher discount rates keep pressure on long-duration equities.
- CLARITY Act dead in the Senate. Cloture vote failed 50-41. No US crypto market structure framework in 2026 with the next legislative window post-midterm election.
- Oil at $109 keeps the inflation case alive. Saudi East-West pipeline damage and Middle East tension mean Warsh has a fresh reason to signal more hikes.
- Dot plot could show two more hikes. Markets are pricing 36% odds on two more hikes by mid-March 2027. A hawkish dot plot forces a repricing of the curve.
- Long-duration tech is exposed. NVDA, META, and the AI complex sit at the front of any dot-plot hawkish surprise given their duration profile.
Asian Markets This Morning
Asian equities are broadly higher this morning despite the Wall Street drop Tuesday, as traders position ahead of the Fed decision. Nikkei 225 gained 0.7% to 63,923.00 despite Japan reporting a fourth straight month of trade deficit in August. Kospi rose 1.4% to 6,717.97, recovering from Tuesday when semiconductor weakness dragged the index 0.85% lower. Hang Seng edged up 0.2% to 24,715.18 and the Shanghai Composite climbed 0.7% to 3,891.60. Indian Nifty 50 futures are in the green. The bid is a bet that whatever Warsh says tonight, Asian chip and tech supply chains stay intact.
What Moved Wall Street Today
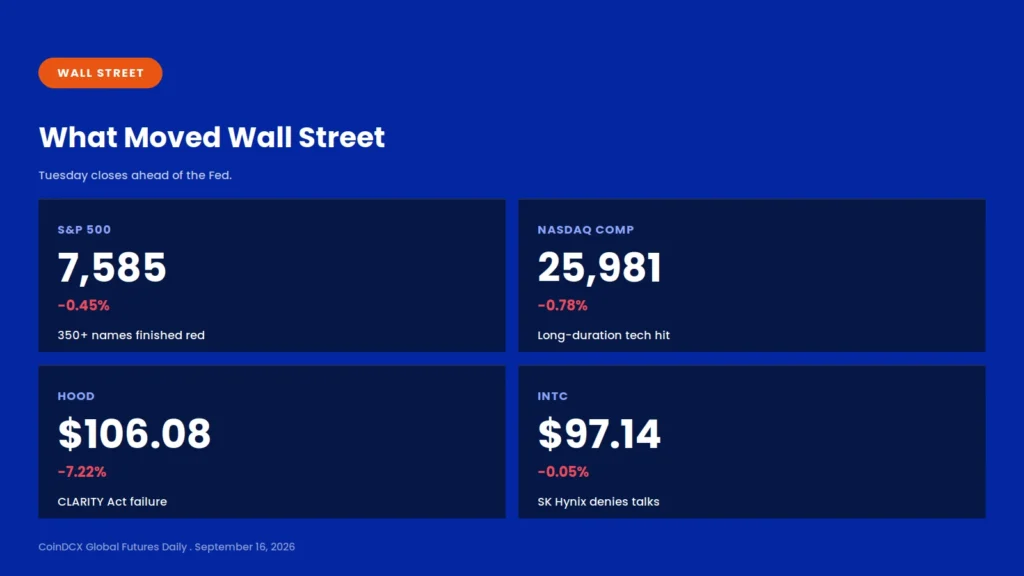
Wall Street closed lower Tuesday as traders refused riskier bets in the countdown to the Fed decision. The S&P 500 fell 0.45% to 7,585.73. Nasdaq Composite dropped 0.78% to 25,981.57. Dow Jones lost 328.09 points or 0.63% to 52,093.11. Almost 350 firms in the S&P 500 finished red. The 10-year Treasury yield touched 5.00% intraday, its highest level in nearly two decades, after a weak $13B sale of 20-year bonds.
Crypto-linked stocks took the hardest hits after the Senate blocked the CLARITY Act cloture vote at 50-41 Monday. HOOD closed $106.08 down 7.22%. COIN fell about 9% to $174.80. CRCL dropped about 5.5%. The bill needed 60 votes to advance and the failure ends US crypto market structure legislation for 2026.
Semiconductor stocks were mixed. INTC closed $97.14 essentially unchanged after SK Hynix publicly denied reported talks on US memory chip production with Intel. The story broke via Walter Bloomberg and LiveSquawk within minutes of each other. AMD gained about 2%, Coherent added nearly 2%, and Qualcomm advanced more than 4%. Brent crude settled around $109 after Saudi East-West pipeline attacks kept the geopolitical premium in the tape.
Assets in Focus
NVDA
Nvidia is the barometer for how the AI capex trade weathers the Fed decision. Tuesday brought a supporting data point: FT reported OpenAI’s annualized revenue surpassed $40B last month, up about 20% since GPT-5.6 launched. The customer revenue side of the AI trade is showing up, which is what Nvidia needs to keep the buildout story credible. Watch $220 as the near-term resistance and $205 as the level that keeps the trend intact. A hawkish dot plot with two more 2026 hikes penciled in pressures NVDA most among the mega-caps because of its duration profile.
INTC
Intel closed Tuesday at $97.14 essentially unchanged after SK Hynix denied reported talks on US memory chip production with Intel. The story was that Intel needed a memory partner for its US foundry push, and the denial removes that catalyst from the near-term picture. Watch $95 as the level that decides whether the whole memory-partnership pop this month reverses. Above $100, the Intel foundry narrative can rebuild toward $105 where it was last priced.
CRCL
Circle closed Tuesday down about 5.5% after the Senate blocked the CLARITY Act cloture vote 50-41. The bill needed 60 votes, Republicans hold 53 seats, and at least 7 Democrats needed to cross the aisle. Democratic objections centered on the ethics package not covering the Trump family adequately. The next legislative window is post-midterm election, meaning no US crypto framework in 2026. CRCL sits at the stablecoin, payments, and digital-infrastructure intersection where regulatory clarity would have mattered most.
AMZN
Amazon announced 1,000+ new same-day delivery hubs by 2031 with a $6.8B budget for 2026-27 alone. The number confirms the read that Amazon capex stays big even into a higher rate regime. Watch $240 as the near-term breakout level and $225 as the support that keeps the post-earnings uptrend intact.
SPCX (pre-IPO Perp)
Pre-IPO SpaceX Perp on CoinDCX Global Futures is the private-market angle that stays largely insulated from the Fed decision itself. The OpenAI $40B ARR read-across is direct for Starlink revenue as another private company scaling fast. SPCX has been trending on the CoinDCX app for weeks and is the pre-IPO name to lean on when public crypto stocks are under pressure and traders want private-market exposure.
Index Levels to Watch
S&P 500 closed Tuesday at 7,585.73. Reference points for context: 7,500 sits as first downside pivot after the decision, then 7,400. On the upside, 7,700 and 7,800. Nasdaq Composite closed 25,981.57 with support at 25,500 and 25,000, resistance at 26,200 and 26,500. Dow Jones closed 52,093.11 with support at 51,500 and 51,000 and resistance at 52,800.
Disclaimer
This blog is provided for informational and educational purposes only and does not constitute investment advice, a recommendation, or a solicitation to buy or sell any asset. Trading in financial derivatives, including Global Futures, involves substantial risk and may not be suitable for all investors. Levels and reference points mentioned are for context only and should not be interpreted as entry or exit signals. Please do your own research and consult a SEBI-registered advisor before making investment decisions. CoinDCX and its affiliates are not responsible for any losses incurred based on the information provided in this article.
Frequently Asked Questions
Q1. What is priced into the Fed decision tonight?
Rate futures show 93% odds on a 25 bp hike, moving the target range from 3.50-3.75% to 3.75-4.00%. It would be the first US rate hike since 2023.
Q2. What time does the Fed decision release?
The statement releases at 11:30 PM IST. Warsh's press conference starts at 12:00 AM IST.
Q3. Why is the dot plot the trade tonight?
The 25 bp move is already priced. The Summary of Economic Projections and dot plot show where FOMC members see rates over the next year and can move markets more than the decision itself.
Q4. What is JPMorgan's downside call if the Fed does not hike?
JPMorgan expects the S&P 500 to fall 1.25% to 1.75% if Warsh does not deliver the hike. A dovish surprise would call the Fed's inflation resolve into question.
Q5. What happened to Robinhood, Coinbase, and Circle Tuesday?
The Senate blocked the CLARITY Act cloture vote 50-41. HOOD fell 7.22% to $106.08. COIN dropped about 9% to $174.80. CRCL fell about 5.5%. The failure ends US crypto market structure legislation for 2026.