

Riyadh air-raid alerts returned as Houthi strikes hit Saturday. Oil is falling, US futures are green, Trump-Xi meets Thursday. What retail should watch.
TLDR
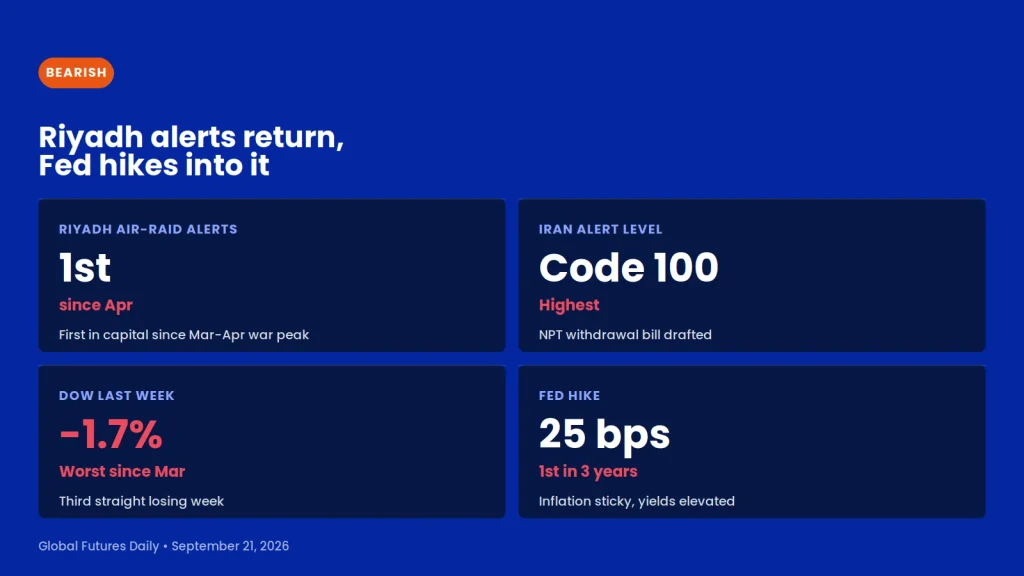
- Saudi Arabia issued air-raid alerts for Riyadh over the weekend, the first in the capital since the height of the US-Iran war in March and April
- Iran-backed Houthis attacked Saudi Arabia with missiles and drones on Saturday
- The US State Department issued fresh security warnings across the Middle East
- Iranian lawmakers submitted a bill to withdraw from the Nuclear Non-Proliferation Treaty, still pending Speaker approval
- Iran is reportedly at Code 100, its highest military alert level
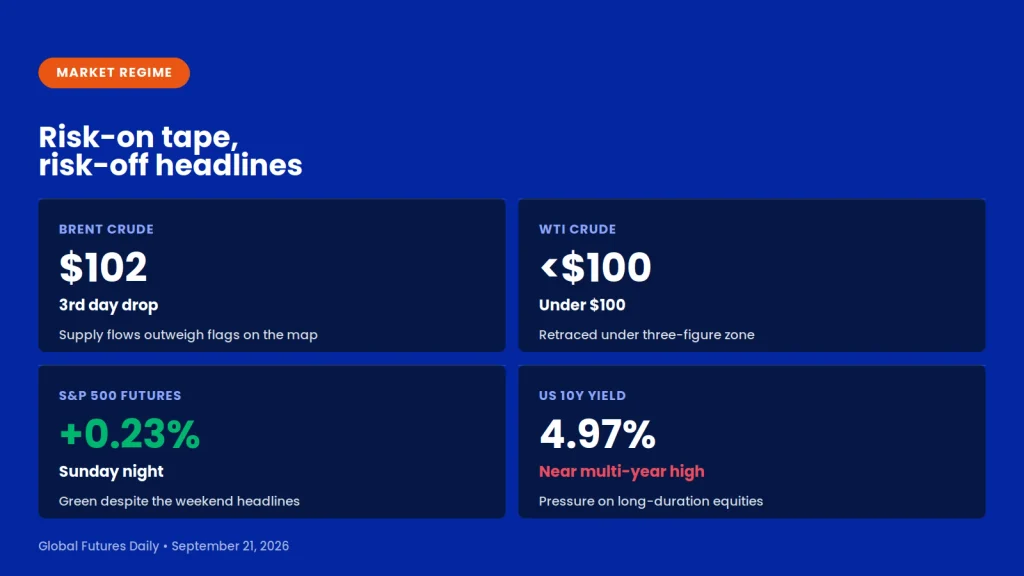
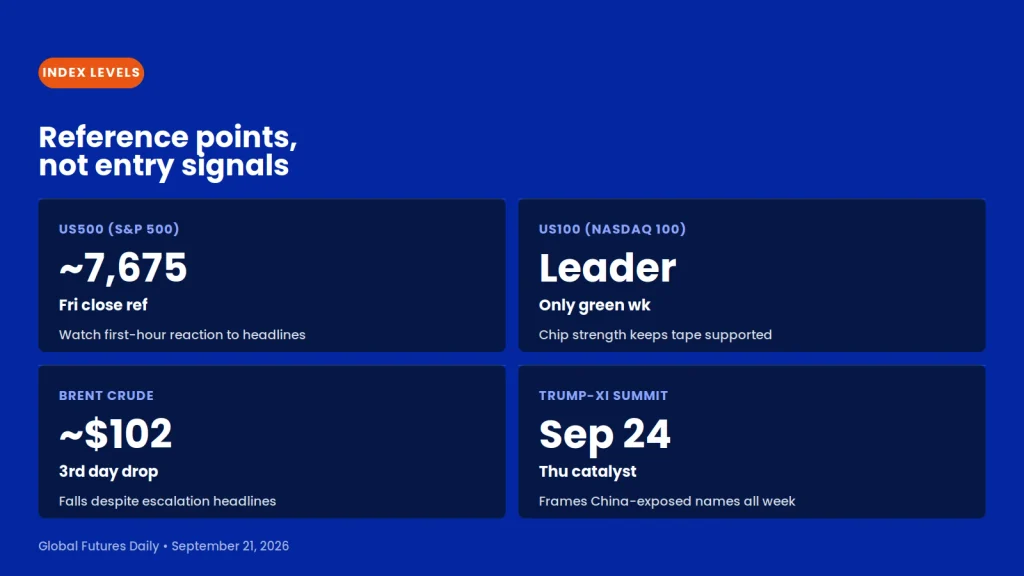
- But oil is falling. Brent is near $102, WTI slipped below $100, both dropping for a third day
- US stock futures are green Sunday night: S&P 500 futures up 0.23%, Nasdaq-100 futures up 0.27%, Dow futures up 0.25%
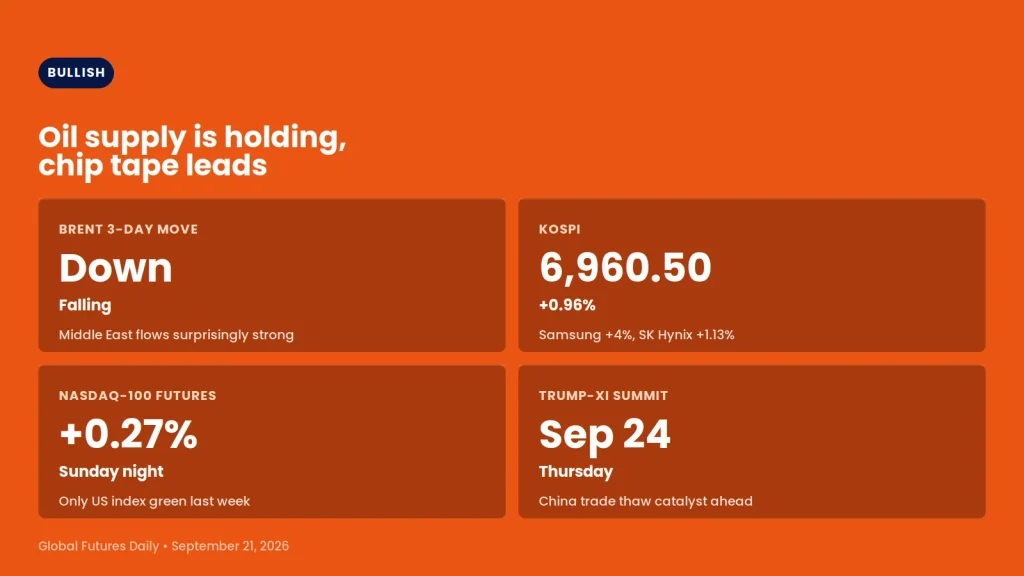
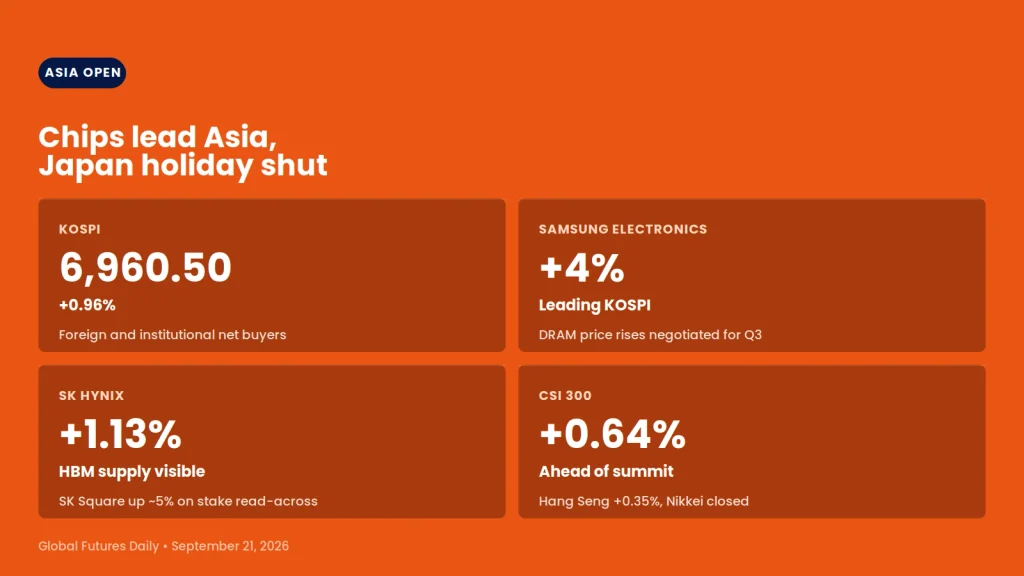
- KOSPI is up 0.96% at 6,960.50 on Samsung Electronics up 4% and SK Hynix up 1.13%
- Trump-Xi summit on Thursday September 24 anchors the week for China-exposed names
Market Regime
The setup for the week is a classic risk-on despite risk-off headlines. Iran, Houthi, Saudi, and NPT stories dominate the ticker but the market is trading like an economic slowdown, not a war. Brent is well below its September high, WTI has retraced under $100, and both are on a three-day drop. That is the tell. Traders are looking at supply flows first, and only then at flags on the map.
What could break this regime is a single incident that turns the calm into a real Hormuz threat, or an oil-facility strike markets cannot look through. JPMorgan noted Middle East oil flows are surprisingly strong despite East-West pipeline disruption, though the same note flagged flows are still 6.1 million barrels a day below the 2025 average. The buffer is thin. Trump-Xi Thursday is the second variable. The meeting will either confirm the trade-sentiment thaw or crack it, and BABA and other China-exposed names sit on that outcome.
Bullish Factors
- Oil is falling despite escalation headlines. Brent is near $102 and WTI below $100, both on a three-day drop.
- Saudi output is being restored. JPMorgan analysts note Middle East oil flows are surprisingly strong despite pipeline disruption.
- KOSPI is up on Samsung Electronics and SK Hynix strength, which typically front-runs the US chip complex.
- US futures were green Sunday night with S&P 500 futures at plus 0.23%, Nasdaq-100 futures at plus 0.27%.
- Trump-Xi Thursday could confirm the US-China trade thaw and lift BABA, JD, PDD, and other China names.
- Nasdaq was the only major US index green last week, and tech resilience continues into today.
- Ark Invest’s Eva Ados made a fresh bullish case for SpaceX moats. Her argument is that infrastructure, not the LLM, is where the real AI value sits.
Bearish Factors
- Saudi Arabia’s Riyadh air-raid alerts are the first since the March-April height of the war. That is a real escalation on the calendar, not just a headline.
- Iran is reportedly at Code 100 alert level. Iranian Parliament is drafting a withdrawal bill from the Nuclear Non-Proliferation Treaty.
- The Dow snapped a three-week winning streak last week with its worst weekly loss since March, down about 1.7%.
- The US 10-year Treasury yield is at 4.97%, near multi-year highs. That pressures long-duration equities.
- The Federal Reserve raised interest rates last week for the first time in three years. Inflation is sticky and yields are elevated.
- Any single Hormuz-facing shipping incident would flip the calm oil regime instantly. Fresh supply news would move the tape in seconds.
- SoftBank credit is stretched. Its 2031 dollar bond yield is at 8.2%, up from 6.7% in January, and the AI credit story is drawing hard questions.
Asian Markets This Morning
- KOSPI is up 0.96% at 6,960.50 as of 9:14 AM local. It opened at 6,938.34, plus 0.64% from the previous close.
- Samsung Electronics is up over 4%. SK Hynix is up 1.13%. SK Square, which has a large stake in SK Hynix, is up close to 5%.
- Foreign investors and institutions are net buyers on the KOSPI today. Individual investors are net sellers.
- Nikkei 225 is closed for Japan’s Respect for the Aged Day holiday.
- Hong Kong Hang Seng is up 0.35% early. Mainland China’s CSI 300 is up 0.64%.
- Regional theme: chip strength is leading Asia. Middle East risk is contained on the tape for now.
What Moved Wall Street Today
- The S&P 500 traded lower on the week. The Dow finished its third straight losing week.
- Only the Nasdaq closed the week green, up about 0.7%. Tech held up better than the broader tape.
- The Dow’s weekly loss was the worst since March, down about 1.7%.
- The 10-year Treasury yield sat at 4.97% Friday, near multi-year highs.
- Brent finished Friday around $103 to $104. WTI was in the $99 to $100 zone.
- Positioning ahead of the Fed hike week had rate-sensitive names underperforming.
- Chip stocks held up on the tape despite the broader rate pressure. That momentum carries into today’s session.
Assets in Focus
XLE (Energy Select Sector SPDR)
- The most direct read on the Iran story. Watch this before headlines hit anything else.
- Falling with oil despite escalation. That price action is telling you traders expect supply to keep flowing.
- Any single Hormuz-facing incident is a fast gap risk here.
- Reference points only, not entry or exit signals.
NVDA
- The Korea chip tailwind is favorable at the open, with SK Hynix and Samsung Electronics leading Asia.
- Trending list mainstay on the CoinDCX Global Futures app.
- Any Iran headline can be a fade for tech longs given valuation.
- The Ark Invest SpaceX story reinforces the picks-and-shovels narrative: infrastructure is the moat, and NVDA sells the shovels.
- Reference points only, not entry or exit signals.
SPCX (SpaceX Pre-IPO Perp)
- Ark’s Eva Ados made a fresh bullish call: SpaceX AI could become a leading AI business.
- Her argument: the real AI moat is infrastructure, not the LLM. Space-based data centre ambitions strengthen the thesis.
- Strongest proof: competitors becoming customers. Amazon relies on SpaceX launches. Anthropic uses Colossus One.
- SPCX is only tradeable in India via the pre-IPO Perp product on CoinDCX Global Futures.
- Pre-IPO perp is not a normal spot exposure. Understand funding and expiry before entry.
- Reference points only, not entry or exit signals.
BABA
- Trump-Xi summit on Thursday September 24 is the anchor catalyst this week.
- Any tariff, critical minerals, or AI framework announcement lifts Chinese e-commerce names.
- The recent Q1 FY27 print showed margin compression. Position size accordingly.
- Read-across candidates on any BABA move: JD, PDD, BIDU, and other Hang Seng tech.
- Reference points only, not entry or exit signals.
SNDK
- Rate-sensitive high-beta memory play. Same memory supercycle tailwind as the Korean names.
- Exposed if the 10-year yield stays above 5%.
- Not directly on the Iran story, but part of the broader chip complex.
- Reference points only, not entry or exit signals.
Index Levels to Watch
- US500 (S&P 500): Friday close reference around 7,675. Watch how the tape reacts to any Iran headline in the first hour of the US session.
- US100 (Nasdaq 100): The only major index that closed green last week. Chip strength is the reason to watch this over the S&P 500 today.
Disclaimer
This content is for informational and educational purposes only. It does not constitute investment advice, financial advice, trading advice, or any other sort of advice or recommendation. All levels and references mentioned are reference points for context, not entry or exit signals. Past performance does not guarantee future results. Global markets carry significant risk. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions. CoinDCX and its affiliates do not endorse or take responsibility for any trading decisions made based on this content.
Frequently Asked Questions
Q1. Why is oil falling if Iran just escalated again?
Because supply is being restored on the ground. Saudi shipments are recovering, and JPMorgan analysts note Middle East oil flows are surprisingly strong despite East-West pipeline disruption. Traders are pricing flows, not flags. The move can reverse instantly on a shipping-lane incident.
Q2. What is Iran's Code 100 alert level?
According to reports circulating over the weekend, Code 100 is Iran's highest military alert level, signalling full readiness for large-scale conflict. Iran has warned that any new US strike will trigger immediate and unlimited retaliation. Markets are treating this as a headline risk, not a base case, for now.
Q3. What does an NPT withdrawal actually mean for markets?
If Iran withdraws from the Nuclear Non-Proliferation Treaty, IAEA inspections stop. That removes a transparency check on Iran's nuclear program. The market impact depends on whether a supply shock or a military escalation follows. The bill still needs Parliament Speaker Ghalibaf's approval, so nothing has happened yet on the treaty itself.
Q4. What is the Trump-Xi summit on September 24 about?
The summit is expected to cover tariffs, critical minerals, artificial intelligence, and other economic issues. Any confirmed framework on any of those would move BABA, JD, and other China-exposed names on the CoinDCX Global Futures list.
Q5. Is the chip strength this morning connected to Iran or separate?
Separate. The chip rally is driven by Samsung Electronics negotiating up to 20% quarter-on-quarter DRAM price rises and SK Hynix supply-chain visibility. That is a memory supercycle story. Iran is the risk-off variable sitting beside it, not the catalyst for the chip move.