
Fed hikes 25bps to 3.75-4.00%, first move since July 2023. Warsh warns inflation still too high. Goldman now sees another October hike, India chips scale.
TLDR
The Fed hiked for the first time since July 2023. Chair Kevin Warsh said inflation is too high and has been for too long. The dot plot has 16 of 18 officials pencilling in at least one more 25bps hike this year, and Goldman Sachs has already shifted its call to expect another move in October. Wall Street saw roughly $490 billion wiped from US stocks in 25 minutes during Warsh’s presser, and the Dow closed down 631 points. The Nasdaq Composite held basically flat. Overnight, US futures recovered with NDX up over 1%. In India, Micron said at SEMICON India 2026 that its Sanand plant will assemble hundreds of millions of chips in 2027, up from tens of millions in 2026. MU is on CoinDCX Global Futures, giving Indian traders a direct read on the story.
Market Regime
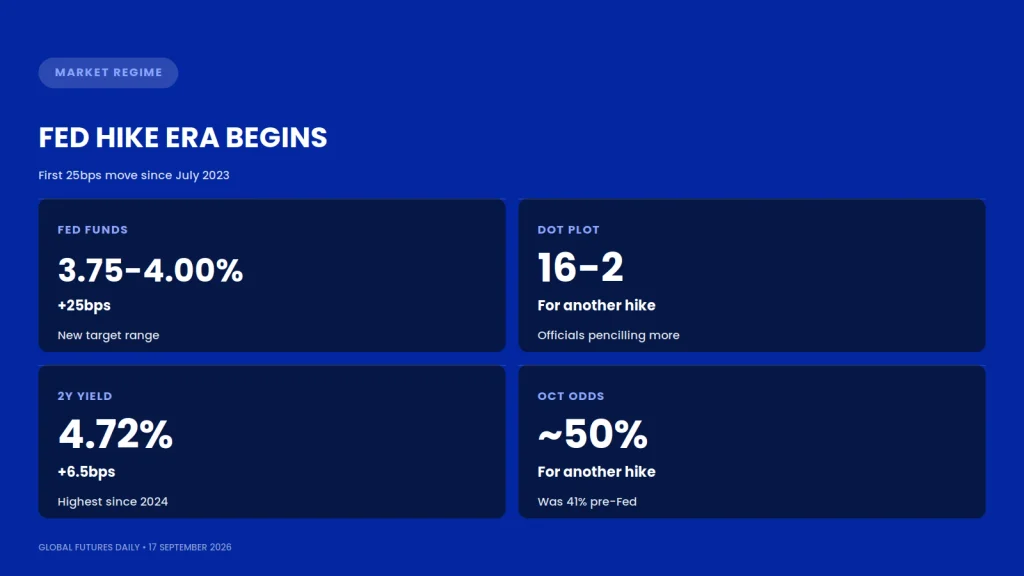
We are back in a tightening cycle. The Fed just delivered its first hike since July 2023, taking the funds range to 3.75-4.00%. Warsh, in his first policy move as Chair, joined a unanimous vote and did not sound close to done. The dot plot shows 16 of 18 officials expecting at least one more 25bps hike this year, and four seeing two. Money markets moved from about 41% October hike odds to roughly 50-50 during the presser. Goldman shifted its call and joined ANZ, BofA, RBC and TD Securities on the same call. This is a fast, coordinated repricing of the near-term Fed path.
What could break the setup: another Iran-driven oil spike that reprices energy stocks and inflation risk in a single day, a soft labor market print that gives Warsh cover to sit longer, or a corporate earnings miss from one of the AI capex leaders that reopens the higher-yields-hit-tech link. Right now, the tape is telling us tech thinks the Fed will not overtighten, while financials and energy have to price for real follow-through. The load-bearing wall of this market is still hyperscaler capex, and Google’s fresh AGI institute announcement kept that signal alive on the very day the Fed hiked.
Bullish Factors
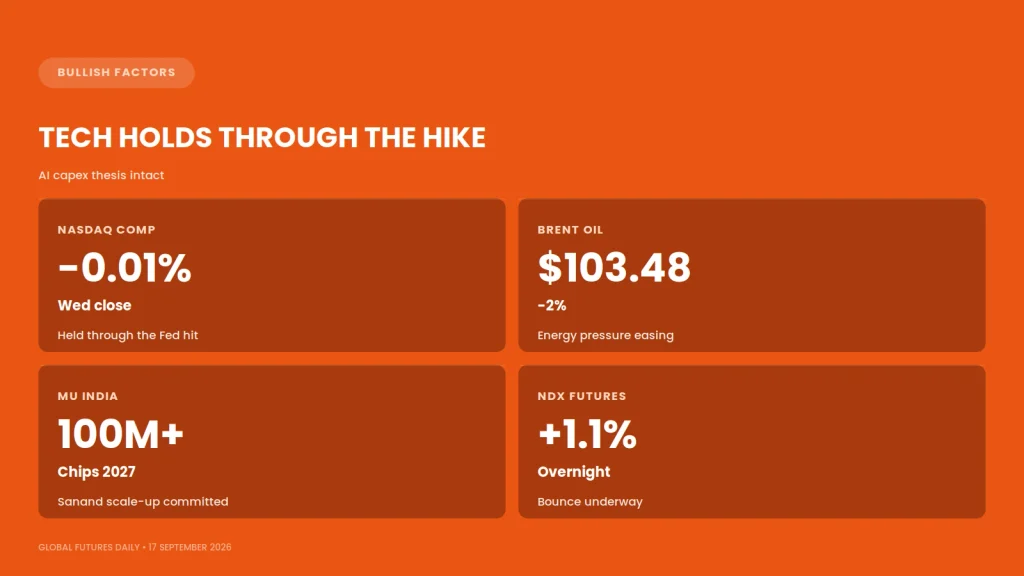
• Nasdaq Composite closed basically flat at minus 0.01%, showing tech absorbed the hike news better than the broader market
• Google and DeepMind announced a new AGI research institute, keeping the hyperscaler capex signal alive
• Micron said at SEMICON India that the Sanand plant will scale from tens of millions of chips in 2026 to hundreds of millions in 2027
• Brent slid over 2% to about $103.48 and WTI is back under $100, easing the energy-side inflation risk
• Overseas tape is constructive with Stoxx 600 up 0.7%, FTSE 100 up 0.8%, ASX 200 up 0.41%
• US futures overnight showed a bounce: Dow futures +379 pts (+0.7%), S&P 500 futures +0.8%, NDX futures +1.1%
Bearish Factors
• The 16 to 2 dot plot signals at least one more 25bps hike this year, with four officials seeing two
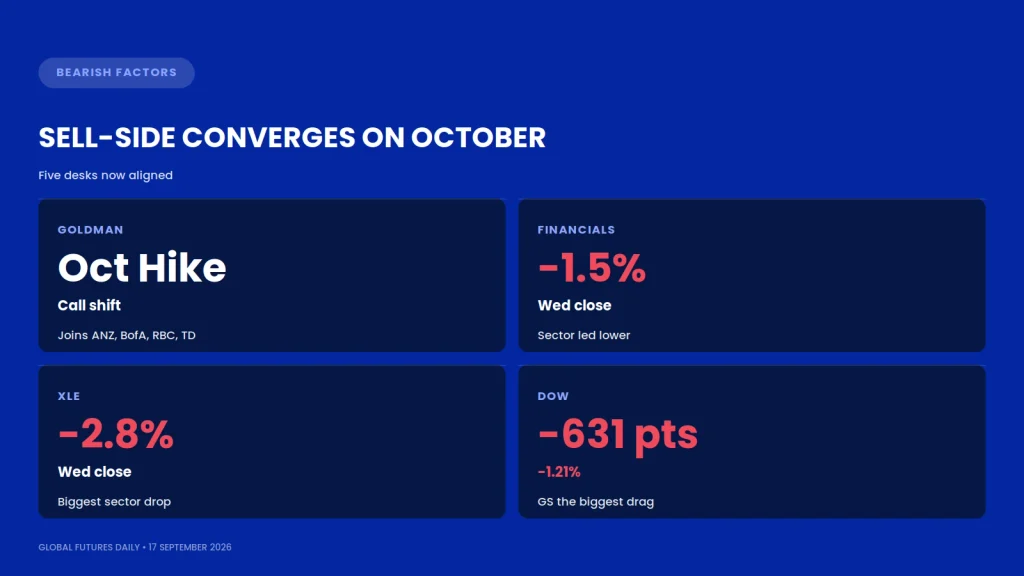
• Goldman Sachs joined ANZ, BofA, RBC and TD Securities in expecting an October follow-up hike
• The 2-year Treasury yield hit its highest level since 2024, above 4.72%
• Warsh called out inflation as too high and too long, pushing back on any expectation of easy money
• Financials sector fell 1.5% Wednesday: GS, V, JPM, BAC, WFC all closed red
• Energy sector XLE fell 2.8%, the largest sector decline, on the oil retreat and higher-rate impact
Asian Markets This Morning
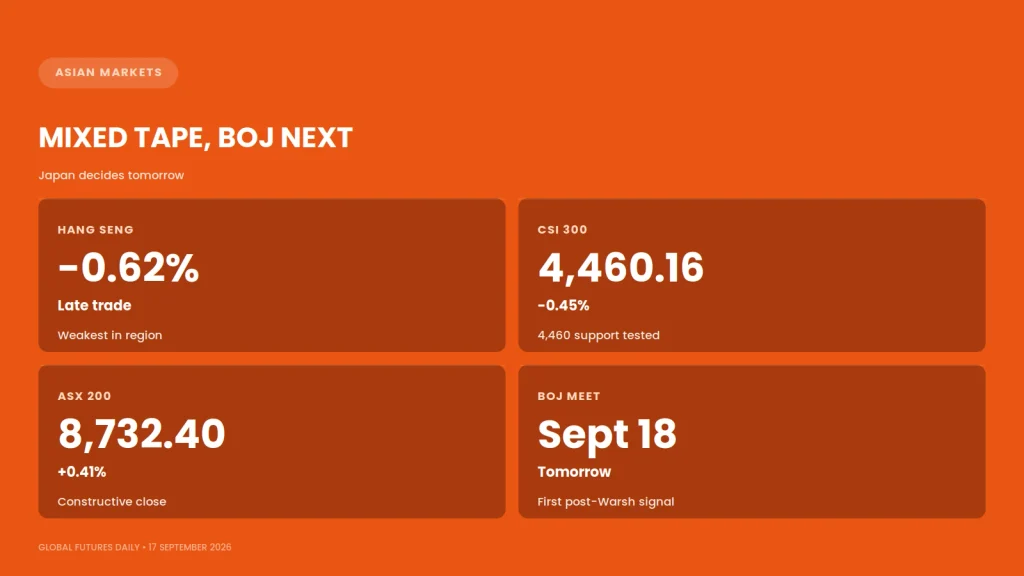
Asia is trading mixed on Thursday as traders digest the Fed decision. Hong Kong’s Hang Seng was down 0.62% in the last hour of trade. Mainland China’s CSI 300 closed 0.45% lower at 4,460.16. Australia’s benchmark ASX 200 rose 0.41% to 8,732.40. Japanese stocks are in wait-and-watch mode ahead of the Bank of Japan decision on Friday, September 18, in what will be the BoJ’s first rate-decision signal since Warsh took the Fed chair. Yen sensitivity is high, and Japanese exporters are already pricing the yen path. Korean semi-linked names should see a read-across from the Micron India news as the broader memory tape stays in focus.
What Moved Wall Street Today
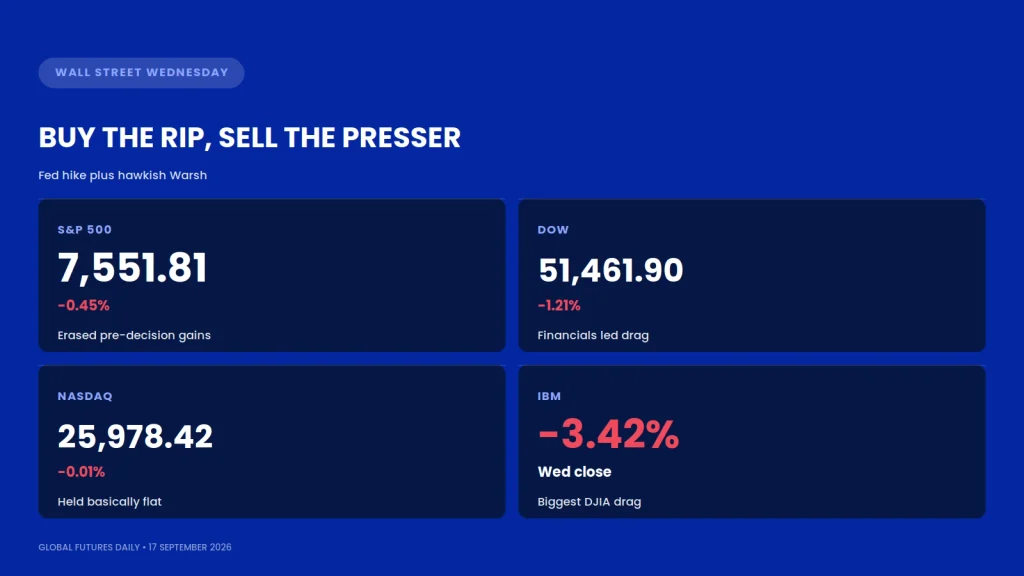
Wall Street opened green Wednesday and stayed there until the Fed decision at 2 PM ET. The Fed delivered its first 25bps hike since 2023, taking the funds range to 3.75-4.00%. The initial reaction was contained, but Warsh’s presser accelerated the selling. In roughly 25 minutes, about $490 billion in market cap was wiped from US stocks. The Dow finished down 631 points at 51,461.90, off 1.21%, with Goldman Sachs itself the biggest single drag at minus 0.94%. The S&P 500 closed at 7,551.81, off 0.45%. The Nasdaq Composite closed at 25,978.42, essentially flat at minus 0.01%. IBM was the biggest DJIA loser at minus 3.42%, followed by ExxonMobil at minus 3.02%. Sector splits: energy XLE fell 2.8%, financials fell 1.5%, and technology absorbed the hit with the AI accelerator tape holding better than the banks.
Assets in Focus
MU (Micron)
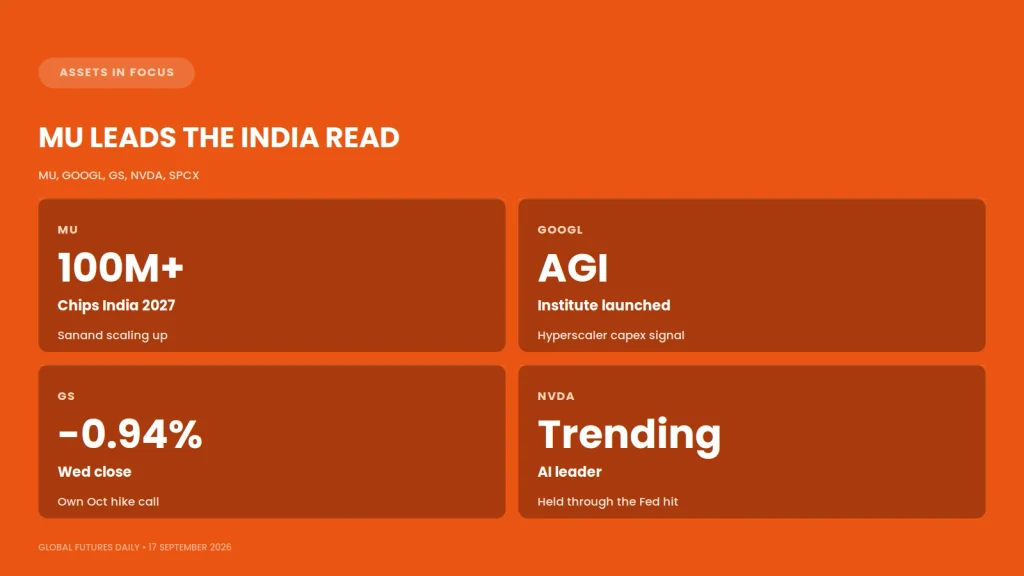
Micron CEO Sanjay Mehrotra said at SEMICON India 2026 that the Sanand plant will scale from tens of millions of chips in 2026 to hundreds of millions in 2027. Made-in-India memory modules are already shipping to Dell for laptops built in India for the Indian market. The facility, opened in February 2026 with $2.75 billion in combined investment, will feature over 500,000 square feet of cleanroom once Phase 1 is fully ramped. MU trades on CoinDCX Global Futures, and the DRAM index on the platform is the broader memory-cycle proxy for retail. SEMICON India 2026 runs through September 19 at Yashobhoomi Convention Centre.
GOOGL
Google and DeepMind announced a new institute to explore AGI. For markets, the signal is that hyperscaler capex intent has not slowed. GOOGL held through the Wednesday selloff and is one of the anchors of the Nasdaq’s resilience trade. Watch it against the broader AI leaders on any follow-through selling.
GS (Goldman Sachs)
Goldman Sachs shifted its Fed call and now expects another 25bps hike in October after Warsh’s presser proved more hawkish than the desk had priced. The bank highlighted the 16 to 2 dot plot split, elevated rate projections, and Warsh’s repeated reference to removing a dose of accommodation. GS was the single biggest drag on the Dow Wednesday, closing minus 0.94%, and remains the cleanest single-name read on how markets price Fed expectations.
NVDA
NVDA is on the CoinDCX Global Futures trending list. The AI accelerator tape held through the Fed hit even as rate-sensitive names sold off, telling us the AI capex thesis is still the load-bearing wall of the market. The Google AGI institute announcement and Micron India news both feed adjacent parts of the same trade.
Index Levels to Watch
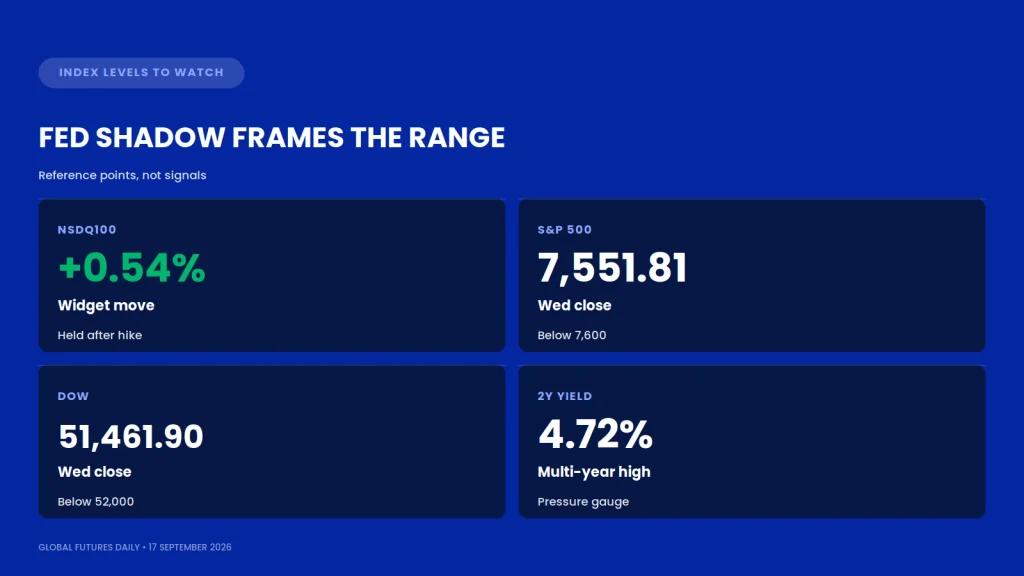
Reference points for context only, not entry or exit signals. NSDQ100 was up 0.54% on the CoinDCX platform widget at time of writing. S&P 500 settled Wednesday at 7,551.81 after erasing pre-decision gains. The Dow held above 51,000 despite the 631-point drop and closed at 51,461.90. The 2-year Treasury yield sits above 4.72%, the highest since 2024, and is the pressure gauge on both financials and rate-sensitive parts of the equity tape. Watch how the 10-year responds if the 2-year keeps grinding higher.
Disclaimer
This content is for informational purposes only and does not constitute investment advice, financial advice, trading advice, or any other sort of advice. CoinDCX is not a SEBI-registered investment advisor. Any levels or price references are provided as contextual data points only and should not be interpreted as entry, exit or trade signals. Trading and investment carry risk, including the risk of loss. Users should consult independent financial advisors and perform their own research before making any trading or investment decisions. All third-party trademarks and logos are property of their respective owners.
Frequently Asked Questions
Q1. What did the Fed do on September 16, 2026?
The FOMC raised the target range for the federal funds rate by 25bps to 3.75-4.00%, the first Fed rate hike since July 2023.
Q2. Is another Fed rate hike coming in October 2026?
The Fed's dot plot has 16 of 18 officials expecting at least one more 25bps hike this year. Goldman Sachs, ANZ, BofA, RBC and TD Securities have all shifted to expect an October follow-up. Money markets are pricing October at roughly 50 percent hike probability.
Q3. Why did the Nasdaq hold up despite the Fed hike?
The AI capex thesis stayed intact. Google's DeepMind AGI institute announcement and continued hyperscaler spending on NVDA hardware kept large-cap tech supported. The Nasdaq Composite closed essentially flat at minus 0.01% even as the Dow fell 631 points.
Q4. What is the big India chip story on September 17?
Micron said at SEMICON India 2026 that its Sanand semiconductor assembly and test plant will scale from tens of millions of chips in 2026 to hundreds of millions in 2027. Made-in-India memory modules are already shipping to Dell for laptops built in India.
Q5. Which CoinDCX Global Futures assets should Indian traders watch first?
MU for the India-anchored memory read, GOOGL for hyperscaler capex, GS as the Fed proxy, NVDA on the platform's trending list, and SPCX for AI infra sentiment. The DRAM index on the platform is the broader memory-cycle proxy.